WATCH THE FULL VIDEO HERE
Moving to Denver in 2026 or 2027? Here's what out-of-state homebuyers need to know before purchasing a house in Colorado.
If you're thinking about moving to Denver, Colorado, you've probably already done some research.
You know about the mountains.
You've heard about the snow.
You probably know Denver has some traffic, that the altitude takes some getting used to, and that housing isn't exactly cheap.
But after living in Colorado for more than 43 years and helping buyers navigate the Denver real estate market, I've found that some of the most expensive surprises aren't necessarily the things people research before relocating.
They're the things that don't always jump out at you when you're scrolling through homes on Zillow.
Things like:
A property tax bill that could be significantly higher than the amount shown on a real estate listing.
A Colorado homeowners insurance policy with a hail deductible that could leave you paying thousands of dollars out of pocket.
Home inspection issues involving radon, sewer lines, or other hidden problems that could become very expensive after closing.
And these aren't minor details.
Depending on the property, we're potentially talking about $5,000, $10,000, or even $15,000 in unexpected expenses.
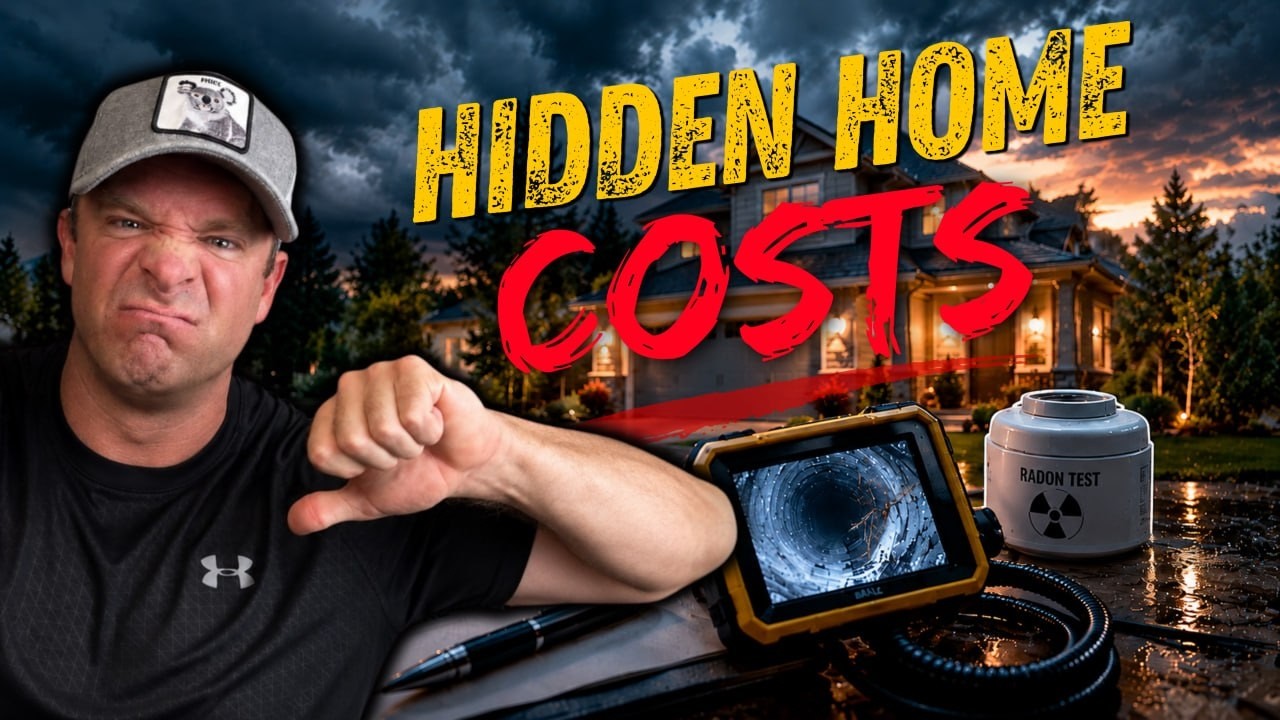
That's why in this week's episode of Living in Denver, I'm sharing three things I want every buyer to understand before purchasing a home in the Denver metro area—especially if you're relocating from another state.
Because the purchase price is only part of the story.
Quick Answer: What are the biggest hidden costs of buying a home in Denver?
Three important costs Denver homebuyers should investigate are property taxes, Colorado homeowners insurance deductibles, and specialized home inspections. Property taxes can change after a purchase, hail and wind deductibles may require significant out-of-pocket payments, and issues involving radon or underground sewer lines can create unexpected expenses. Understanding these risks before closing can help buyers evaluate the true cost of owning a home in Colorado.
1. Denver Property Taxes:
Why the Amount on Zillow May Not Be What You'll Pay
Let's start with something that surprises a lot of people moving to Colorado.
The property tax amount displayed on a real estate listing isn't necessarily what you'll pay after buying the house.
This is particularly important if you're relocating to Denver from another state and using online home-search tools to estimate your monthly mortgage payment.
You find a house you love.
You look at the estimated mortgage payment.
You see the property taxes.
Everything appears to fit your budget.
But have you confirmed whether that tax estimate accurately reflects the property's current valuation, exemptions, applicable taxing districts, and potential future reassessments?
That's where things can get complicated.
How do property taxes work in Denver, Colorado?
Colorado property taxes are based on a combination of factors, including:
The property's assessed value
Applicable residential assessment rates
Local mill levies
Taxing districts
Applicable exemptions or adjustments
The property's classification and assessment history
Property taxes vary by location, even within the broader Denver metro area.
A house in Denver County can have a different tax situation from a property in Jefferson, Arapahoe, Douglas, Adams, or Boulder County.
And even two properties with similar market values can have different tax bills depending on their taxing districts and other circumstances.
Do Colorado property taxes automatically increase when you buy a house?
No. Colorado does not automatically reset a property's assessed value to your purchase price simply because the home sells.
That's an important distinction.
However, Colorado property values are reassessed periodically, tax laws and assessment rates can change, local mill levies can vary, and certain exemptions or property-specific circumstances may affect the amount shown in historical tax records.
So although buying a home doesn't automatically trigger a purchase-price-based tax reset, you still shouldn't assume the seller's previous tax bill will accurately represent your future tax liability.
Why the seller's tax bill can be misleading
Imagine you're looking at a Denver-area home and the listing shows relatively low annual property taxes.
Before relying on that figure, I'd want to understand:
Does the property currently have any exemptions or special circumstances affecting the bill?
What is the latest assessed value?
Which taxing districts apply?
Is the property in a metro district?
What changes could affect future tax bills?
Has the listing information been verified against county records?
Those are much better questions than simply accepting the annual tax number displayed online.
Metro districts can matter, too
This is another issue that can catch buyers by surprise, especially in certain newer Colorado communities.
Some neighborhoods are located within metropolitan districts, which may levy property taxes to help finance infrastructure, improvements, or services.
That doesn't automatically make a neighborhood a bad place to buy.
But it can materially affect your property tax bill.
And if you're comparing homes in different Denver suburbs, it's important to understand those differences.
What I'd recommend before buying
Before writing an offer—or at least before your applicable contract deadlines expire—I'd want to:
Verify the property's current tax information with the county assessor or treasurer.
Review the applicable taxing districts and mill levies.
Check for exemptions or special circumstances.
Understand the property's assessment history.
Have the lender calculate a realistic monthly payment using appropriate tax assumptions.
The goal is to understand what you can reasonably expect to pay—not simply what the previous owner paid.
2. Colorado Hail Insurance:
Your Deductible Could Cost Thousands
This is a BIG one.
If you're moving to Denver from another state, you might not realize just how important hail and wind coverage can be when buying a home in Colorado.
Colorado gets severe thunderstorms.
We get hail.
And hail can damage roofs, gutters, siding, windows, and other exterior components.
That's one reason I want buyers thinking about homeowners insurance before they're close to the closing table.
What is a wind and hail deductible?
Your homeowners insurance deductible is the amount you're responsible for paying toward a covered claim before the insurer pays the covered amount, subject to the terms of the policy.
But here's what some buyers don't realize:
Certain Colorado homeowners insurance policies have separate wind or hail deductibles expressed as a percentage of the home's insured dwelling coverage.
That's very different from assuming every claim has a flat $1,000 or $2,500 deductible.
Example: How much could a 2% hail deductible cost?
Let's say your home has:
$600,000 in insured dwelling coverage.
And your policy has a:
2% wind and hail deductible.
Here's the math:
$600,000 × 2% = $12,000
That means you could be responsible for the first $12,000 of covered wind or hail damage under that deductible, depending on the policy and claim.
And notice something important:
The deductible is calculated using the insured dwelling coverage—not necessarily the home's purchase price or market value.
That's why you need to review the actual insurance quote.
What if your deductible is 1%, 2%, or 5%?
Using a hypothetical $600,000 dwelling coverage amount:
| Wind/Hail Deductible | Potential Out-of-Pocket Deductible |
|---|---|
| 1% | $6,000 |
| 2% | $12,000 |
| 5% | $30,000 |
These are illustrations, not quotes or claims about what every Colorado policy offers.
But they demonstrate why a percentage-based deductible deserves serious attention.
Why this matters when comparing Denver homes
Imagine two houses with similar purchase prices.
One has a newer roof, a favorable insurance quote, and coverage terms you're comfortable with.
The other has an older roof and a substantially higher premium or deductible.
Those two properties might have very different ownership costs.
And the difference may not be obvious from their Zillow listings.
What about roof age and condition?
Roof age, materials, condition, claim history, location, and other underwriting factors can affect insurance availability, pricing, and coverage terms.
That's why I'd want to know:
How old is the roof?
What type of roof is it?
Has it experienced previous hail damage?
Has it been repaired or replaced?
Are permits or warranties available?
What coverage will the insurer provide?
Are there separate wind and hail deductibles?
Does the policy have roof-related limitations?
And I'd want the insurance professional—not the listing description—to explain the policy.
Get an insurance quote early
One of the simplest ways to reduce surprises is to get a property-specific homeowners insurance quote early in the buying process.
Don't assume your insurance will cost the same as it did in another state.
And don't assume two Denver-area homes with similar prices will have identical premiums or deductibles.
I want buyers to know the insurance numbers while they still have time to make informed decisions.
3. Denver Home Inspections:
Radon and Sewer Lines Can Be Expensive Surprises
This is probably the area where I see the biggest opportunity to protect buyers through good due diligence.
Especially when we're talking about older Denver homes.
Denver has a huge variety of housing stock.
You'll find historic Denver Squares, Craftsman bungalows, Tudors, mid-century ranches, newer construction, and just about everything in between.
And while I love the character of older homes, they can come with systems and infrastructure that deserve extra attention.
Two inspections I strongly encourage buyers to consider are:
Radon testing.
And:
A sewer scope inspection.
They're not substitutes for a general home inspection.
They're additional ways to investigate potential problems that may not be visible during a typical showing.
What is radon, and why is it important in Colorado?
Radon is a naturally occurring radioactive gas that can enter homes through the ground.
You can't see it.
You can't smell it.
And you generally can't tell whether a home has elevated radon levels without testing.
Long-term exposure to elevated radon increases the risk of lung cancer.
Colorado is known for having significant radon potential, which is why testing is particularly relevant for buyers.
Should you get a radon test when buying a house in Denver?
Yes. I strongly recommend radon testing as part of a Denver-area home purchase.
A house doesn't need to be old to have elevated radon.
And a newer home isn't automatically protected.
If elevated levels are found, radon mitigation systems can often reduce concentrations.
But you want to know about the issue before closing, when you still have an opportunity to evaluate the findings, obtain professional advice, and potentially negotiate.
What is a sewer scope inspection?
A sewer scope is an inspection in which a qualified professional uses a specialized camera to examine the interior of an accessible sewer line.
It's especially worth considering for older Denver-area homes.
Why?
Because many established Denver neighborhoods have older underground sewer infrastructure.
Depending on the property, sewer lines may contain materials such as clay or cast iron, and age, tree roots, deterioration, or ground movement can create problems.
A sewer scope may identify issues such as:
Root intrusion
Cracks
Separated pipe sections
Blockages
Deterioration
Low spots or bellies
Other visible pipe defects
Why sewer problems can be so expensive
Imagine buying a beautiful older brick bungalow in Denver.
The kitchen looks great.
The floors have been refinished.
The basement is finished.
Everything looks move-in-ready.
Then, a few months after closing, the sewer line backs up.
You discover significant root intrusion or a damaged underground pipe.
Depending on the location, depth, accessibility, and repair method, sewer repairs or replacements can potentially cost thousands—or tens of thousands—of dollars.
That's a painful surprise.
And it's one reason I recommend considering a sewer scope before you own the house, rather than waiting until there's a problem.
Are sewer scopes only necessary for older homes?
No.
Older homes may have more obvious age-related risks, but newer sewer lines can also have installation defects, damage, or other problems.
I'd consider the home's age, location, trees, known history, and other factors when recommending specialized inspections.
What about the general home inspection?
A qualified general home inspector can evaluate many accessible components of the property.
But a general inspection doesn't necessarily include specialized testing or a full evaluation of every system.
Depending on the house, additional evaluations may include:
Sewer scope
Radon testing
Roof inspection
Structural engineering evaluation
HVAC inspection
Electrical evaluation
Plumbing evaluation
Moisture investigation
The goal isn't to find a perfect house. It's to understand the house you're buying.
What Could These Three Denver Homebuying Surprises Actually Cost?
Let's look at some simplified examples.
| Potential Surprise | Why It Matters |
|---|---|
| Higher-than-expected property taxes | Can increase ongoing monthly housing costs |
| $12,000 hail deductible | May create a major out-of-pocket expense after covered storm damage |
| Sewer line replacement | Could result in a substantial unexpected repair bill |
| Elevated radon | May require professional mitigation |
| Older roof with insurance limitations | Could affect coverage, premiums, or future replacement costs |
Not every buyer will encounter these problems.
And not every issue means you should walk away from a property.
But you should know what you're getting into.
That's what good due diligence is for.
The True Cost of Buying a Home in Denver Goes Beyond the Mortgage
This is something I talk about frequently with buyers relocating to Colorado.
The question shouldn't be only:
“Can I afford to buy this house?”
It should also be:
“Can I comfortably afford to own this house?”
Your total housing costs may include:
Mortgage principal and interest
Property taxes
Homeowners insurance
Mortgage insurance, when applicable
HOA dues
Utilities
Maintenance
Repairs
Future system replacements
Other property-specific expenses
And that doesn't include the lifestyle costs that come with living in Colorado.
If you moved here to ski, hike, bike, camp, travel, and enjoy the outdoors, you probably don't want every extra dollar going toward your house.
The home should support the lifestyle you moved here for.
Not make that lifestyle impossible to afford.
Moving to Denver?
Here's How I'd Approach Buying a Home
If you're relocating from another state, I'd start with a few important steps.
Step 1:
Determine your comfortable monthly payment
Not simply the maximum amount a lender says you can borrow.
Your comfortable payment should account for taxes, insurance, HOA costs, and the rest of your financial picture.
Step 2:
Narrow down the right Denver neighborhoods and suburbs
Denver is a big metro area.
A home in Wheat Ridge can offer a very different experience from one in Littleton, Arvada, Parker, Golden, or Castle Rock.
Location affects lifestyle, commuting, housing options, and property-specific expenses.
Step 3:
Review property taxes and insurance before committing
Don't wait until the end of the transaction to discover the complete ownership costs.
Step 4:
Build a property-specific inspection strategy
Older bungalow?
Sewer scope and radon testing are high on my list.
Home with visible drainage issues?
We may need further evaluation.
Roof with questionable age or hail damage?
Let's get the right professional involved.
The property should help determine the inspections we order.
Step 5:
Understand the findings before your deadlines
Colorado real estate contracts have important deadlines.
I want buyers to understand the relevant inspection, insurance, title, and other contract timelines so they can investigate concerns and make informed decisions while their contractual options remain available.
Are These Reasons Not to Buy a Home in Denver?
Not at all.
I love Colorado.
I've spent more than four decades here.
And I think Denver and the surrounding communities offer some incredible lifestyle opportunities.
But loving Colorado doesn't mean ignoring the realities of homeownership.
Hail happens.
Property taxes require research.
Older homes have older systems.
Radon is worth testing for.
And no home is completely maintenance-free.
The goal isn't to scare you away from buying.
It's to help you avoid being surprised by things we could have investigated beforehand.
Watch: 3 Things to Know Before Buying a Home in Denver
In this week's episode of Living in Denver, I'm breaking down three things that can catch homebuyers off guard—especially people moving here from another state.
You'll learn:
Why the property tax number on a listing deserves a closer look
How Colorado hail insurance deductibles can create significant out-of-pocket expenses
Why I strongly recommend radon testing and sewer scope inspections
How to think beyond the listing price
What to investigate before buying a house in Denver
These aren't necessarily the most exciting parts of buying a home.
But they're some of the most important.
Watch the full episode on my Living in Denver YouTube channel: @livingindenver303.
Frequently Asked Questions About Hidden Homebuying Costs in Denver
What are the hidden costs of buying a house in Denver?
Important costs to investigate include property taxes, homeowners insurance premiums and deductibles, HOA dues, maintenance, and potential repairs. Denver buyers should also consider specialized inspections such as radon testing and sewer scopes.
Do property taxes increase when you buy a home in Colorado?
Not automatically. Colorado does not simply reset a property's taxable value to the purchase price at closing. However, reassessments, changes in tax rates, taxing districts, exemptions, and other circumstances can affect future tax bills.
Why are property taxes different between Denver suburbs?
Property taxes depend on assessed value, applicable assessment rates, local mill levies, taxing districts, and other factors. Two similarly priced homes in different counties or metro districts can have different tax bills.
How much is a Colorado hail insurance deductible?
It depends on the insurance policy. Some policies have percentage-based wind or hail deductibles. For example, a 2% deductible on $600,000 of insured dwelling coverage would equal $12,000.
Is homeowners insurance expensive in Denver?
Costs vary considerably by property, roof condition, coverage, deductible, insurer, and other factors. Buyers should obtain property-specific quotes rather than relying on generic estimates.
Should I get a radon test when buying a home in Denver?
Yes. Radon testing is strongly recommended because Colorado has significant radon potential. Elevated levels can occur in both older and newer homes, and testing is the way to determine the home's radon concentration.
Do I need a sewer scope when buying a house in Denver?
I strongly recommend considering one, especially for older homes. A sewer scope can help identify root intrusion, damaged pipes, blockages, deterioration, and other issues that may not be visible during a general inspection.
How much does sewer line replacement cost in Denver?
Costs vary widely depending on pipe length, depth, accessibility, material, damage, excavation, and repair method. Significant sewer repairs can cost thousands or tens of thousands of dollars, so property-specific professional estimates are essential.
Should I avoid buying an older home in Denver?
No. Older Denver homes can offer excellent locations, mature landscaping, architectural character, and distinctive layouts. The key is understanding the condition of the roof, sewer, electrical, plumbing, foundation, HVAC, drainage, and previous renovations.
What inspections should I get when buying a house in Colorado?
Start with a qualified general home inspection. Depending on the property, additional inspections may include radon testing, sewer scope, roof evaluation, structural assessment, HVAC, plumbing, electrical, and moisture investigations.
Is Denver a good place to buy a home in 2027?
That depends on your financial readiness, timeline, neighborhood preferences, and long-term goals. The right decision should account for the complete cost of ownership, not just the purchase price or mortgage rate.
What's the biggest mistake people make when moving to Denver?
One common mistake is focusing on the home price and neighborhood without fully investigating the property's taxes, insurance, condition, maintenance obligations, and future ownership costs.
The Bottom Line:
Know What You're Buying Before You Buy It
If you're thinking about moving to Denver or buying a home in Colorado, don't stop at the purchase price.
Understand the property taxes.
Read the homeowners insurance quote.
Know the hail deductible.
Test for radon.
Consider a sewer scope.
Investigate the expensive systems.
And make sure the complete ownership costs fit your budget.
Because the best time to discover a potential $10,000 problem is before the house becomes yours.
About Adam Lang | Living in Denver
I'm Adam Lang, a Denver-area Realtor®, Colorado native, Certified Real Estate Negotiation Expert, and creator of the Living in Denver YouTube channel.
I've lived in Colorado for more than 43 years, including growing up in the west Denver metro, and I've watched the area evolve considerably over the decades.
Today, I help buyers, sellers, and people relocating to Colorado understand the Denver housing market, compare neighborhoods, evaluate homes, navigate inspections, and develop smart real estate strategies.
My approach is about more than helping you find a house.
It's helping you understand what you're buying, what it could cost to own, and whether the location fits the life you want to live.
Through Living in Denver, I share weekly educational videos about moving to Denver, Denver neighborhoods and suburbs, Colorado real estate, buying a house in Denver, and what it's actually like to live along the Front Range.
Moving to Denver in 2026 or 2027?
Let's Build Your Buying Strategy.
If you're considering relocating to Denver, I'd be happy to help you make sense of the process before you start touring houses.
I offer a free 30-minute Denver Real Estate Strategy Session where we can discuss:
Your budget and comfortable monthly payment
Your relocation timeline
Denver neighborhoods and suburbs
Commute and lifestyle preferences
Home styles and property age
Property taxes
Homeowners insurance
HOA costs
Inspection strategy
Current Denver housing inventory
Negotiating opportunities
Your next steps
Whether you're moving in three months or just starting to research Colorado, the goal is to help you make an informed decision.
You can schedule your strategy session and access free homebuyer resources at AdamSellsDenver.com.
Because buying the right house is important. Understanding the real cost of owning it is just as important.
Check out this article next