WATCH THE FULL VIDEO HERE
If you were buying a home in Denver right now, would you rather own a house—or a condo?
A few years ago, that question might have mostly come down to lifestyle and budget.
In 2026, it's gotten a LOT more interesting.
That's because Denver's single-family home market and condo/townhome market aren't behaving the same way.
Detached single-family homes are generally selling faster.
Many condos and townhomes are sitting on the market longer.
Buyers may have more negotiating power on attached properties.
But there's a catch:
A condo that looks $100,000 cheaper on Zillow may not actually feel $100,000 cheaper once you calculate the complete monthly payment.
HOA dues matter.
Insurance matters.
Special assessments matter.
Property taxes matter.
And the financial condition of the HOA itself can matter.
So in this week's episode of Living in Denver, I'm breaking down what the Denver housing market is showing us right now, where buyers may have more negotiating leverage, and the questions I'd want answered before buying a condo or townhome in Colorado.
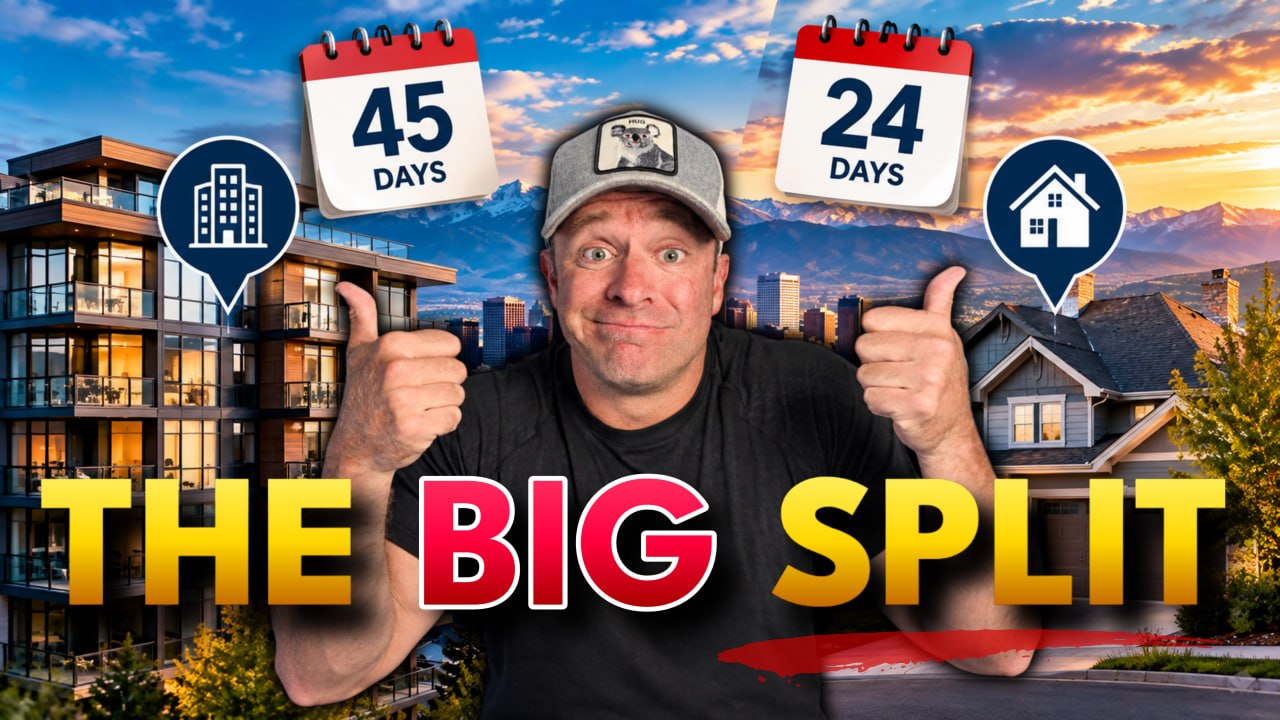
Quick Answer: The Denver condo and townhome market currently offers buyers more inventory and, in many cases, more negotiating leverage than the detached single-family market. In August 2026, attached homes in the Denver metro had a median 45 days in MLS compared with 24 days for detached homes, while attached inventory was up 9.94% year over year. But a lower condo purchase price doesn't automatically mean lower overall housing costs. Buyers need to evaluate HOA dues, insurance, reserves, special assessments, maintenance responsibilities, financing, and the complete monthly payment before deciding whether a condo, townhome, or detached house provides better value. (dmarealtors.com)
Is It Better to Buy a House or Condo in Denver Right Now?
There isn't one answer for every buyer.
That's because you're really making two decisions:
What kind of property fits your lifestyle?
And:
Which property makes the most financial sense?
Those aren't necessarily the same thing.
A condo might give you:
A lower purchase price
Less exterior maintenance
Amenities
A more central location
Potentially more negotiating leverage in today's market
A detached house might give you:
More privacy
A yard
More control over the property
No shared walls
Fewer HOA restrictions in some communities
Different long-term ownership considerations
But those are generalizations.
A downtown Denver high-rise condo is completely different from a suburban townhome.
And a 1950s Denver ranch without an HOA is completely different from a newer detached house in a master-planned community with significant HOA dues.
That's why I wouldn't start with:
“Are condos better than houses?”
I'd start with:
“What am I actually getting for my total monthly cost?”
The Denver Condo Market and Single-Family Home Market Are Telling Two Different Stories
This is where the current Denver housing data gets interesting.
According to the Denver Metro Association of Realtors' August 2026 Market Trends Report, detached and attached homes are behaving very differently.
In August:
Detached inventory was DOWN 4.21% year over year.
Meanwhile:
Attached inventory was UP 9.94% year over year.
And attached properties were taking substantially longer to sell.
The median days in MLS were:
Detached homes: 24 days
Attached homes: 45 days
Attached median prices were also down 4.87% year over year, while detached median prices were essentially flat from the previous year. (dmarealtors.com)
That's not a small difference.
And it helps explain why buyers may experience two completely different Denver real estate markets depending on what type of property they're shopping for.
Denver Condos and Townhomes May Give Buyers More Negotiating Power
Go back one month and the difference becomes even clearer.
In July 2026, DMAR reported that detached homes had just under three months of inventory and a median of 17 days in MLS.
Attached homes—condos and townhomes—had approximately 5.7 months of inventory and a median 40 days on market.
DMAR characterized that attached inventory level as buyer's-market territory. (dmarealtors.com)
What does that potentially mean if you're buying a condo in Denver?
More inventory can sometimes mean:
More properties to choose from
More time to make a decision
Less competition
More price reductions
More opportunities to negotiate
Potential seller concessions
Potential inspection flexibility
Less pressure to waive protections
But I wouldn't assume every condo is negotiable.
A great unit in a desirable building that's priced correctly can still attract significant interest.
Real estate is property-specific.
The market data gives us context.
Then we analyze the individual property.
Why Are Denver Condos Taking Longer to Sell?
There's probably not one single reason.
Affordability remains a major factor throughout the Denver housing market.
But attached properties have another expense buyers have to consider:
HOA dues.
And those dues can substantially change the affordability calculation.
DMAR specifically noted in its June 2026 market analysis that the attached segment was increasingly being affected by deferred maintenance and rising HOA-related costs. (dmarealtors.com)
That's why looking only at the asking price can be misleading.
A Condo That's $100,000 Cheaper May Not Feel $100,000 Cheaper
Let's use a simplified example.
Imagine you're comparing:
House A
Purchase price:
$600,000
HOA:
$0 per month
Condo B
Purchase price:
$500,000
HOA:
$600 per month
At first glance:
The condo is $100,000 cheaper.
That sounds significant.
But now add:
$600 × 12 = $7,200 per year in HOA dues.
Over five years, assuming the dues never increase, that's:
$36,000.
And that still doesn't tell us whether the HOA is well funded, whether insurance costs are increasing, or whether a special assessment is coming.
That doesn't mean the $500,000 condo is a bad deal.
The HOA may cover expenses you'd otherwise pay yourself.
But it means we need to compare:
Total cost versus total cost.
Not:
Purchase price versus purchase price.
What Do Denver Condo HOA Fees Actually Cover?
This is one of the first questions I'd ask when evaluating a condo.
HOA dues may cover different things depending on the community.
Potential expenses can include:
Exterior maintenance
Roof
Landscaping
Snow removal
Common-area maintenance
Building insurance
Amenities
Elevators
Pools
Fitness facilities
Water
Trash
Security
Professional management
Reserve funding
But never assume something is included simply because another condo you've owned covered it.
Read the actual HOA documents for the specific community.
A $500 monthly HOA fee that covers substantial expenses may look very different from a $500 fee in an association with significant deferred maintenance and inadequate reserves.
High HOA Fees Aren't Automatically Bad
This is an important distinction.
Buyers sometimes see:
HOA: $700/month
and immediately decide:
“That's terrible.”
Maybe.
But not necessarily.
The better question is:
What am I getting for that $700?
Imagine one association charges $350 per month but has very little money in reserves and substantial upcoming repairs.
Another charges $700 but has healthy reserves, maintains the building properly, and includes several expenses you'd otherwise pay separately.
Which association is financially healthier?
You can't answer that from the monthly dues alone.
Low HOA Fees Aren't Automatically Good Either
This might be even more important.
Cheap HOA dues can look fantastic right up until the special assessment arrives.
An association has to pay for major common expenses somehow.
Depending on the property, that could eventually include:
Roof replacement
Exterior work
Siding
Elevators
Parking structures
Paving
Plumbing
Mechanical systems
Common-area renovations
Other major capital projects
If the association hasn't adequately planned and saved for those expenses, owners may eventually be asked to contribute additional money.
That's where HOA reserves become important.
What Are HOA Reserves?
Think of an HOA reserve fund as money the association sets aside for major future repairs and replacements.
Instead of waiting for a $1 million project and then asking owners to suddenly come up with the money, a well-planned association may gradually accumulate reserves.
The Colorado Division of Real Estate notes that Colorado law does not require HOAs to conduct reserve studies, although associations are required to adopt a reserve-study policy addressing when a study is prepared and whether there's a funding plan for recommended work.
That's an important distinction for Colorado condo buyers.
Don't assume every HOA has a recent professional reserve study just because one would be useful.
Ask for it. (dre.colorado.gov)
What Is a Special Assessment?
A special assessment is an additional charge an HOA can levy on owners to help pay for expenses beyond the association's normal budget and available reserves, subject to the association's governing documents and applicable law.
Here's a simplified example:
Imagine a condominium building needs a major exterior repair.
The association doesn't have enough money in reserves.
Owners could potentially face an additional assessment to cover the shortfall.
Suddenly, the condo that looked affordable based on its purchase price and monthly HOA dues has another cost attached to it.
That's why I want buyers asking:
Are there any current special assessments?
Have any been approved?
Are any being discussed?
What major projects are coming?
How much money does the HOA have in reserves?
Why HOA Reserve Studies Matter When Buying a Denver Condo
A reserve study can help provide information about major components the association is responsible for, their expected useful lives, anticipated replacement costs, and the association's funding strategy.
Colorado's Division of Real Estate uses an educational example showing why reserve funding matters: lower-funded associations can face a greater likelihood of needing special assessments, while stronger reserve positions provide more capacity to handle future expenses. (dre.colorado.gov)
So if I'm helping someone evaluate a condo or townhome, I'm not interested only in:
“How nice is the unit?”
I'm also interested in:
“How healthy is the association?”
When You Buy a Condo, You're Buying More Than the Unit
This is one of the biggest differences between evaluating a condo and evaluating a detached home.
With a detached house, we're primarily investigating the individual property.
With a condo, we're evaluating:
The unit + the building/community + the association.
DMAR made essentially this point in its August report while discussing Denver's attached luxury market: buyers weren't just evaluating individual residences; deferred maintenance, dated common areas, and the overall building experience could affect how they viewed a property. (dmarealtors.com)
That's exactly how I'd approach a condo purchase.
A gorgeous kitchen inside Unit 407 doesn't tell us whether the building itself is financially healthy.
What HOA Documents Should You Review Before Buying a Condo in Colorado?
The exact documents available can vary, but depending on the transaction and community, I'd want buyers paying attention to information involving:
Current HOA budget
Financial statements
Reserve information
Reserve study, if available
Insurance information
Governing documents
Rules and regulations
Meeting minutes
Current assessments
Pending special assessments
Upcoming capital projects
Litigation, if applicable
Owner occupancy
Rental restrictions
Pet restrictions
Parking
Maintenance responsibilities
This isn't exciting reading.
Nobody dreams about spending Saturday night reading HOA meeting minutes.
But there can be extremely valuable information buried in those documents.
HOA Meeting Minutes Can Tell You a Lot
Imagine you're reading recent HOA meeting minutes and repeatedly see discussion about:
Roof problems.
Insurance increases.
Water intrusion.
Elevator repairs.
Parking-garage repairs.
A possible special assessment.
Would you want to know that before buying?
Absolutely.
Meeting minutes can sometimes help reveal issues that aren't obvious when you're standing inside a beautifully staged condo.
Colorado Condo Insurance Is Another Piece of the Puzzle
Insurance has become a major homeownership issue throughout Colorado.
For a condo buyer, there can be two layers of insurance to understand:
The association's master policy
and
The owner's individual condo policy.
The exact responsibilities depend on the building, governing documents, and insurance policies.
Colorado's Division of Insurance specifically maintains resources for homeowners and HOAs because of challenges involving Colorado's property-insurance market. (doi.colorado.gov)
Before buying, I'd want to understand:
What does the HOA master policy cover?
What is the master-policy deductible?
What insurance does the individual owner need?
Have premiums increased substantially?
Have deductibles changed?
Are insurance costs contributing to higher HOA dues?
Could owners have financial responsibility for certain losses or deductibles?
Those are questions worth discussing with both the HOA and your insurance professional.
Why HOA Insurance Costs Can Affect Your Monthly Payment
Suppose an HOA's insurance premium rises significantly.
The association still has to pay it.
That expense may ultimately affect the HOA's budget and dues.
So even though you don't personally choose the association's master insurance carrier, changes in the building's insurance expenses can affect your cost of ownership.
This is one reason I'd be cautious about comparing condos based only on:
Purchase price + mortgage rate.
There's more to the equation.
House vs. Condo:
Which Has the Lower Monthly Payment?
You have to run the actual numbers.
A condo may have a significantly lower purchase price but a significant HOA payment.
A detached house may cost more but have little or no HOA expense.
Your complete housing payment can include:
Principal
Interest
Property taxes
Homeowners or condo insurance
HOA dues
Mortgage insurance when applicable
Then I'd separately consider maintenance and potential future expenses.
That's the number I care about.
Condo vs. Townhouse:
What's the Difference?
Buyers often use condo and townhouse interchangeably, but they're not necessarily the same thing.
“Townhouse” often describes the physical style of the property.
“Condominium” generally refers to the legal form of ownership.
So a property that physically looks like a townhome may legally be organized as a condominium.
That distinction can affect:
Ownership responsibilities
Insurance
Maintenance
HOA structure
Financing
Don't assume based on how the property looks.
Verify how it's legally structured.
Is Buying a Denver Condo a Bad Investment?
Not automatically.
The current attached market is softer than the detached market overall, but that doesn't mean every Denver condo is a bad purchase.
A condo may provide:
A lower entry price
Access to a location you otherwise couldn't afford
Lower exterior-maintenance responsibility
Amenities
Walkability
A simpler lifestyle
An opportunity to negotiate in today's market
For the right buyer, those can be significant advantages.
The better question is:
Is this specific condo in this specific building at this specific price a good fit for my finances and lifestyle?
That's something we can actually evaluate.
Is Buying a Denver House a Better Investment Than a Condo?
Again, I'd be careful with blanket statements.
Detached homes and condos have different:
Price points
Land components
Maintenance responsibilities
Buyer pools
HOA considerations
Locations
Amenities
Supply-and-demand dynamics
And today's Denver market demonstrates that those segments can behave very differently.
Detached homes currently have tighter inventory and are generally selling faster than attached homes.
But that doesn't guarantee what happens to an individual property—or what either segment will do in the future.
Where Might Denver Condo Buyers Have More Negotiating Leverage?
This is where current market conditions can create opportunity.
A condo that's been sitting on the market for:
40 days.
60 days.
90 days.
may be a very different negotiation from a detached home that received three offers during its first weekend.
Depending on the property, I'd investigate:
Days on market
Price reductions
Competing listings
Recent comparable sales
Seller motivation
Current offers
HOA condition
Upcoming assessments
Property condition
Then we can decide whether there's an opportunity to negotiate things such as:
Purchase price
Seller concessions
Closing costs
Interest-rate buydown
Inspection issues
Closing date
Other transaction terms
List price isn't always the price you have to pay.
Should First-Time Denver Buyers Consider Condos?
Absolutely—as long as they understand what they're buying.
For some first-time buyers, a condo or townhome may provide a more attainable entry point into Denver homeownership.
You may be able to buy in a location where a detached house would be outside your budget.
You may also prefer having less exterior maintenance.
But don't buy a condo simply because the purchase price looks cheaper.
Before making an offer, understand:
The complete monthly payment.
The HOA.
The insurance.
The reserves.
The possibility of assessments.
The building itself.
Your future resale market.
That's a much better way to evaluate affordability.
Who Might Prefer a Condo or Townhome?
An attached property may make sense if you value:
Lower purchase price relative to nearby detached homes
Lower exterior maintenance
Walkability
Urban location
Amenities
Lock-and-leave convenience
Less yard work
More negotiating leverage in the current market
A condo can also make sense for someone who simply doesn't want the responsibilities that come with maintaining a detached house.
There's nothing wrong with that.
Who Might Prefer a Detached House?
A detached home may make more sense if you prioritize:
Privacy
A yard
No shared walls
Greater control over the property
Outdoor space
Storage
Potentially fewer HOA restrictions
More separation from neighbors
But remember:
No HOA doesn't mean no maintenance costs.
With a detached home, you may personally be responsible for the roof, siding, landscaping, snow removal, exterior repairs, and other expenses that an HOA may cover in an attached community.
That's why the financial comparison needs to be fair.
House vs. Condo:
Don't Compare HOA Fees to $0
This is one of the more subtle mistakes buyers can make.
Let's say:
Condo HOA = $500/month
and:
Detached home HOA = $0
It's tempting to say the detached house is automatically $500 cheaper each month.
Not necessarily.
What does that $500 condo fee cover?
If it includes exterior maintenance, snow removal, landscaping, water, trash, building insurance, amenities, and reserve funding, you need to account for those things when comparing the detached house.
The house may not have an HOA bill.
But eventually:
You are the HOA.
The roof?
Yours.
Exterior paint?
Yours.
Landscaping?
Yours.
Snow?
Yours.
Major repairs?
Yours.
That's why I compare ownership costs, not just fees.
10 Things I'd Check Before Buying a Condo in Denver
Before I got excited about the granite countertops or mountain view, I'd want answers to these:
How much are the HOA dues?
What exactly do those dues cover?
How much does the association have in reserves?
Is there a recent reserve study?
Are there current or proposed special assessments?
What major repairs are coming?
What does the HOA's master insurance policy cover?
What are the master-policy deductibles?
What do recent HOA meeting minutes reveal?
Could the HOA or project create financing or resale concerns?
Then I'd add one more:
Does the complete monthly cost still make sense compared with buying a house?
That's the question that ties everything together.
Watch: Should You Buy a House or Condo in Denver?
In this week's episode of Living in Denver, I'm breaking down one of the more interesting questions in the 2026 Denver housing market:
Would you rather own a house—or a condo?
Inside the video, I cover:
🏠 Why detached Denver homes are generally moving faster
🏢 Why many condos and townhomes are taking longer to sell
💰 Where buyers may have more negotiating power
📊 Why attached and detached Denver real estate are behaving differently
💵 Why HOA dues can completely change the affordability calculation
🛡️ Why HOA insurance deserves more attention
⚠️ Why special assessments and reserves matter
📄 What I'd want to investigate before buying into an HOA
Because the cheapest-looking home on Zillow isn't necessarily the cheapest home to own.
Frequently Asked Questions About Buying a House vs. Condo in Denver
Is it better to buy a house or condo in Denver in 2026?
It depends on your budget, lifestyle, location preferences, and the specific property. Current Denver-area data shows attached homes generally have more inventory and are taking longer to sell than detached homes, potentially creating more negotiating leverage for condo and townhome buyers. (dmarealtors.com)
Are Denver condos hard to sell right now?
Attached properties are generally taking longer to sell than detached homes. In August 2026, attached Denver-metro properties had a median 45 days in MLS compared with 24 days for detached properties. That doesn't mean every condo is difficult to sell; building, location, price, condition, HOA health, and demand all matter. (dmarealtors.com)
Is Denver currently a buyer's market for condos?
July 2026 Denver-metro attached properties had nearly 5.7 months of inventory, which DMAR characterized as buyer's-market territory. Conditions vary significantly by location, price point, building, and property. (dmarealtors.com)
Why are Denver condos cheaper than houses?
Condos frequently have less land, shared structures and amenities, different ownership arrangements, and different supply-and-demand dynamics than detached homes. Buyers should also factor HOA dues into the affordability comparison rather than comparing purchase prices alone.
Are high HOA fees always bad?
No. Evaluate what the dues cover, the association's financial health, reserve funding, insurance, amenities, maintenance obligations, and upcoming capital projects. A low fee isn't necessarily better if the association is inadequately prepared for major future expenses.
What is a condo special assessment?
A special assessment is an additional charge imposed by an HOA to help cover association expenses beyond normal dues and available resources, subject to applicable governing documents and law. Buyers should investigate current and proposed assessments before purchasing.
What is an HOA reserve study?
A reserve study evaluates major components an association is responsible for and can help estimate future repair or replacement needs and funding. Colorado doesn't require every HOA to conduct one, although associations must have a policy addressing reserve studies. (dre.colorado.gov)
Should I read HOA meeting minutes before buying a condo?
Yes. Meeting minutes can provide valuable context about maintenance issues, upcoming projects, insurance, budgets, owner concerns, and potential assessments.
Do condo owners need homeowners insurance?
Condo owners generally need individual coverage even when the association has a master insurance policy. The exact coverage responsibilities depend on the HOA documents and policies, so buyers should review the master policy and consult an insurance professional.
Are townhomes better than condos?
Neither is automatically better. Also, “townhome” may describe a building style while “condominium” describes a legal ownership structure. Verify the property's ownership and HOA structure rather than relying on appearance alone.
Are condos good for first-time homebuyers in Denver?
They can be. A condo or townhome may offer a lower purchase price and access to locations where detached homes cost considerably more. But buyers need to evaluate HOA dues, insurance, reserves, assessments, financing, and total monthly cost.
Should I buy a condo because Denver condo buyers have more negotiating power?
Negotiating leverage can be an advantage, but it shouldn't be the sole reason to purchase. First determine whether the property, HOA, location, monthly cost, and long-term ownership structure fit your goals.
The Bottom Line:
Don't Compare the Price. Compare the Entire Ownership Cost.
If you're deciding between a Denver condo, townhome, or single-family house, don't stop at the Zillow price.
A $500,000 condo isn't automatically $100,000 “cheaper” than a $600,000 house.
And a $600 monthly HOA isn't automatically $600 wasted.
You need the complete picture.
Look at:
Purchase price.
Mortgage payment.
Property taxes.
Insurance.
HOA dues.
What those dues cover.
Reserve funding.
Potential assessments.
Maintenance.
The condition of the property or building.
And your lifestyle.
Then ask:
“Which property gives me the combination of lifestyle and total ownership cost that actually makes sense for me?”
That's the question I'd rather answer.
About Adam Lang | Living in Denver
I'm Adam Lang, a Denver-area Realtor®, Colorado native, Certified Real Estate Negotiation Expert, and creator of the Living in Denver YouTube channel.
I've lived in Colorado for more than 43 years, and today I help buyers, sellers, and people relocating to Denver understand not just what a property costs—but what they're actually buying.
That means looking beyond the listing photos and asking questions about Denver neighborhoods, property condition, HOA finances, insurance, inspections, negotiating opportunities, resale considerations, and the complete cost of homeownership.
Through Living in Denver, I publish weekly educational content about Denver real estate, buying a house in Denver, Denver condos and townhomes, Denver neighborhoods and suburbs, moving to Colorado, and what it's actually like to own a home along the Front Range.
House or Condo?
Let's Run the Numbers Before You Decide.
If you're thinking about buying a house, condo, or townhome in Denver, I offer a free 30-minute Denver Real Estate Strategy Session.
We can look at:
Your budget
Comfortable monthly payment
Down payment
Target neighborhoods
House vs. condo options
HOA costs
Current Denver inventory
Days on market
Seller concessions
Negotiating opportunities
Your timeline
Your lifestyle
Your long-term goals
And if we find a condo you love, we'll want to understand the association as carefully as we understand the unit itself.
Because getting a great deal on the purchase price isn't much of a deal if you discover afterward that you didn't understand the HOA.
The goal isn't simply to buy the cheapest property.
It's to buy the property you can comfortably afford to own.
Check out this article next